
From the term sheet to payoff, counsel that stays with your loan.
AM Law works with private lenders, hard-money and bridge lenders, funds, and investor-lenders on Florida real estate loans — fix-and-flip, bridge, commercial, construction, and residential investment. Brandy Abreu, Esq., a partner at the firm, leads this work. We prepare loan documents within 48 hours of a complete term sheet, handle the closing, and issue the title policy ourselves as title agent.
What we handle for private lenders.
You do not need a different firm for the documents, the closing, and the months after funding. We work on fix-and-flip, bridge, commercial, construction, and residential investment loans — and you work with the attorney handling the file.
Loan documents & term sheets
Send us a complete term sheet and we prepare the loan documents within 48 hours — the note, mortgage or other security instruments, and the related papers the closing requires.
Title & closings
We handle the real estate closing and issue the title policy ourselves, as title agent — so the deal, the title work, and the closing table stay in one office, not handed off at the last step.
Post-closing review & title policy
After closing, we review the file before we issue the title policy, and we send you the completed documents so your records are in order — not waiting in a pile somewhere else.
Servicing support after funding
Payoffs, extensions, and loan modifications when the loan needs to change. We also track loan maturity and expiration dates and stay in touch so you are not caught short at the end of the term.
Default & foreclosure
If a borrower falls behind, we can help you evaluate the path forward — a workout or modification where that still makes sense, or lender-side enforcement and foreclosure statewide, in all 67 Florida counties.
Ready to send a deal?
Share a complete term sheet or call the office. Loan documents are prepared within 48 hours of a complete term sheet, and you will hear from the attorney who will handle the work.
Request a ConsultationA clear path from term sheet to maturity.
We keep the process simple, and we stay involved after the closing — including if a borrower later defaults, or files bankruptcy.
Send your term sheet
Share the deal terms — and any existing draft documents — with the office. We will review what you have and confirm when the term sheet is complete.
Documents in 48 hours
We prepare the loan documents within 48 hours of a complete term sheet, and walk you through anything that needs a decision before the closing is scheduled.
We close and issue title
We handle the closing, review the file, and issue the title policy ourselves as title agent. You receive the completed documents for your file.
We stay with the loan
We track maturity and expiration dates, and help with payoffs, extensions, modifications, or foreclosure statewide — in all 67 Florida counties — if the facts change.
We follow the file into bankruptcy court. You do not need new counsel.
AM Law is also bankruptcy counsel. If a borrower files while a foreclosure is underway, the same firm stays on the matter and takes the file into bankruptcy court — led by Gary M. Murphree, Esq., a partner at the firm.
One firm from the term sheet through foreclosure — and into bankruptcy court, if it comes to that.
Private lenders often get passed from a closer to a file clerk to a new lawyer if a borrower files bankruptcy. That is not how we work. You speak with the lawyer handling your matter, we issue the title policy ourselves, and if the loan later goes into default, the same firm can take it through foreclosure and, if needed, bankruptcy court.
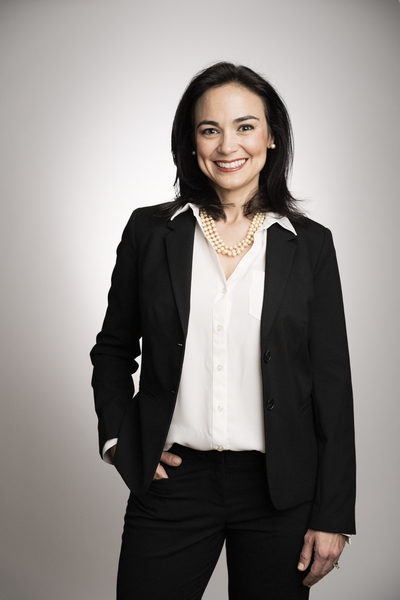
Brandy Abreu, Esq.
Brandy leads the firm’s work with private lenders and property investors — loan documents, closings, title, and enforcement-minded counsel when a loan needs attention. Clear answers, and an office you can actually reach.
Full bio →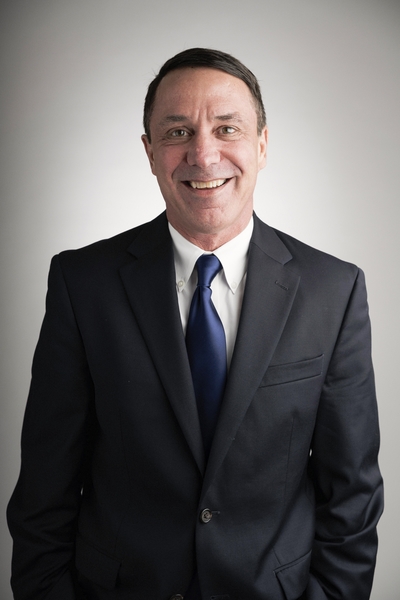
Gary M. Murphree, Esq.
Gary leads the firm’s bankruptcy work. If a borrower files while a foreclosure is underway, he and the firm follow the file into bankruptcy court — so the lender does not have to start over with new counsel.
Full bio →A short guide to Florida lending questions.
The answers below are general information about Florida law, not legal advice for a particular loan. Every deal is different — we are glad to look at yours.
How quickly can you prepare loan documents?
We prepare loan documents within 48 hours of a complete term sheet. A term sheet is the most useful starting point — the parties, the property, the loan amount, the rate and term, and any special conditions. If you already have draft documents, a title commitment, or an entity chart for the borrower, send those too. We will review what you have and confirm when the term sheet is complete.
Do you issue the title policy yourselves?
Yes. AM Law issues the title policy itself, as title agent, and handles the real estate closing. After closing, we review the file before we issue the policy and send you the completed documents for your records.
What if the borrower files bankruptcy during a foreclosure?
You do not need to hire new counsel. AM Law is also bankruptcy counsel, so if a borrower files while a foreclosure is underway, we follow the file into bankruptcy court. That work is led by Gary M. Murphree, Esq., a partner at the firm. The attorney who already knows the loan stays with it.
What interest-rate limits should a private lender know about in Florida?
As a general rule, Florida law treats a contract that charges more than the equivalent of 18 percent per annum simple interest as usurious, when the loan is $500,000 or less. For loans that exceed $500,000, different limits apply, and charging more than 25 percent per annum can raise criminal-usury issues. Points, fees, and how they are spread over the term of the loan can affect the effective rate. Certain loans and lenders are treated differently under the statute. This is only a starting point — the structure of each loan should be reviewed. (Fla. Stat. §§ 687.02, 687.03, 687.071 (2026).)
How does foreclosure work in Florida, and where do you handle it?
Florida is a judicial-foreclosure state: mortgages are foreclosed in equity, through a court action, rather than by a non-judicial power of sale. How long a particular case takes depends on the court, whether the borrower contests the action, and the facts of the loan. There is no single statutory deadline that covers every foreclosure from filing to sale. We handle lender-side foreclosure statewide, in all 67 Florida counties. (Fla. Stat. § 702.01 (2026).)
When can a borrower redeem the property in a Florida foreclosure?
Under Florida law, the borrower — or the holder of a subordinate interest — may cure the debt and prevent a foreclosure sale at any time before the later of two events: the clerk of court filing a certificate of sale, or the time specified in the foreclosure judgment. After that point, there is no right of redemption under that statute. (Fla. Stat. § 45.0315 (2026).)
Do you stay involved after the loan closes?
Yes. We review the file after closing before we issue the title policy, we send you the completed documents, and we track loan maturity and expiration dates. If the loan later needs a payoff, an extension, a modification, or enforcement — including foreclosure, or bankruptcy court if the borrower files — you already have counsel who knows the file.
Send us your term sheet.
Tell us about the loan you are making — or the loan already on your books that needs attention. We prepare loan documents within 48 hours of a complete term sheet. Consultations are confidential, and reaching out does not create an attorney–client relationship.
Request a confidential consultation.
Use the firm’s consultation form and we will follow up within one business day. Or call and speak with the office directly.
Request a Free Consultationor call 305.441.9530
Submitting a form does not create an attorney–client relationship. We will follow up within one business day.